

ISRAEL | SUB-SAHARAN AFRICA
In Global Guardian's monthly Risk Barometer, our Intelligence Team highlights current global hotspots with the potential to impact your business operations and travel. Read below for analysis on the threats we are closely monitoring this month and click here to subscribe for regular intelligence updates.
Future Composition of Israel’s Government Remains Uncertain
Israel’s 27 October parliamentary election produced a fragmented Knesset and a coalition-building deadlock. While Yashar party leader Gadi Eisenkot received the presidential mandate on 08 November to form the next government, Prime Minister Benjamin Netanyahu remains in office as caretaker amid contested election rhetoric, heightened regional security tensions, and political red lines among prospective coalition partners.
Recommendations
- Businesses and travelers should anticipate episodic political demonstrations in Jerusalem, Tel Aviv, and other major urban centers as coalition negotiations unfold ahead of the 06 December initial deadline.
- Avoid all protests and concentrations of security forces. Anticipate heightened security measures and localized transit disruptions near demonstration sites.
- Israeli strikes on Iran remain a distinct possibility as long as Netanyahu remains prime minister, even in a caretaker capacity.
Situation Report
On 27 October 2026, Israeli voters elected a new 120-seat Knesset in which neither Prime Minister Benjamin Netanyahu’s bloc nor the opposition bloc led by Yashar party chair Gadi Eisenkot secured the 61-seat parliamentary majority required to govern independently.
|
Political Grouping |
Knesset Seats |
Rationale |
|
Netanyahu’s bloc |
53 |
Lost its parliamentary majority; Likud remains the largest single party with 27 seats. |
|
Eisenkot’s opposition bloc |
48 |
Holds the presidential mandate to attempt coalition formation. |
|
Arab-led parties (Ra’am and the Joint List) |
19 |
Outside both main blocs; potentially decisive in determining parliamentary viability. |
Although Netanyahu’s bloc won more seats than Eisenkot’s four-party opposition alliance, President Isaac Herzog formally entrusted Eisenkot with the first opportunity to form a government on 08 November after parties representing 67 lawmakers recommended him for the role. Eisenkot has up to 42 days to form a new government (28 days plus a possible 14-day extension). If he fails, President Herzog has three days to either give another Knesset member the mandate or tell the Knesset speaker that he sees no viable path to a government. A second candidate would receive 28 days, with no extension available. If that process also fails, there is a 21-day window in which at least 61 MKs can jointly nominate a member for prime minister, who then has 14 days to form a government. Failure to find a new prime minister triggers another election.
Following the swearing-in of the new Knesset on 10 November, Eisenkot’s allies initiated steps to replace Netanyahu-backed Knesset Speaker Amir Ohana. At the same time, talks began between Arab-party representatives and senior officials from the ultra-Orthodox United Torah Judaism (UTJ) party regarding potential cooperation around an Eisenkot-led government, while Eisenkot’s Yashar party has signaled openness to ultra-Orthodox participation subject to conditions including universal military service. On 17 November, Yashar’s Matan Kahana was elected speaker receiving 66 votes cast along bloc lines.
Political friction has been compounded by disputes over election integrity and regional security. On 12 November, Central Elections Committee Chairman Justice Noam Sohlberg stated that classified material examined in an election-interference inquiry had not developed into actual evidence and might never do so, reiterating alongside election officials that the vote was conducted properly even as Netanyahu has continued to challenge the outcome.
Separately, Netanyahu and Eisenkot held a roughly two-hour security briefing amid discussions of possible renewed military action against Iran, prompting opposition member Avigdor Liberman to warn against launching military operations without adequate parliamentary oversight.
Analysis
Despite a parliamentary majority opposed to extending Netanyahu’s premiership, the parties needed to replace him remain divided over fundamental ideological and policy differences. Any viable governing arrangement requires at least one faction to retreat from a core campaign pledge.
- The Arab-Party Support Dilemma: A minority government with Eisenkot’s 48-seat bloc receiving outside support on votes from the Arab parties, Ra’am (8 seats), and the Joint List (11 seats), or even including Ra’am in the coalition offers the most direct path to unseating Netanyahu without drawing partners from his outgoing coalition. It should be noted that winning a Knesset confidence vote requires more votes in favor than against rather than an absolute 61-vote majority. However, there is strong internal resistance within Eisenkot’s camp (notably Yisrael Beytenu leader Avigdor Liberman (7 seats)), who has rejected a minority government reliant on Arab-party backing. Forming a minority government is also politically risky for Eisenkot and the other right-of-center members of his bloc who would almost certainly lose support in a subsequent election for relying on non-Zionist parties to pass bills or survive confidence motions.
- The Ultra-Orthodox Conscription Divide: An alternative pathway advocated by Liberman seeks to pair the opposition’s 48 seats with ultra-Orthodox parties UTJ (7 seats) and Shas (6 seats) to reach an exact 61-seat majority without Arab-party reliance. Eisenkot’s bloc campaigned on expanding mandatory service to ultra-Orthodox men, whereas UTJ and Shas view preserving exemptions as an existential priority, and UTJ alone cannot deliver a 61-seat majority without Shas.
- Leadership Deadlock in Unity Scenarios: A unity coalition bringing together Likud and parts of Eisenkot’s bloc would result in an easy parliamentary majority and reduce leverage held by smaller ideological parties. While Likud and much of the opposition share broad policy compatibility, a serious lack of trust remains a barrier. Netanyahu insists on remaining prime minister and Eisenkot is reluctant to serve after him in a rotational premiership, considering recent precedent. In 2020, the de facto Leader of the Opposition Benny Gantz formed a unity government with Benjamin Netanyahu, but it collapsed over a state budget dispute before Gantz’s scheduled turn to occupy the Prime Minister’s Office.
Looking Forward
On 14 November, Eisenkot stated that Likud (Netanyahu’s party) could enter a future government under his exclusive leadership with “recognition of the principles I have laid out and a break with the extremists…” The statement also called on Likud and allied Religious Zionism to prove they are "committed to genuine political partnership" by voting for a new parliament speaker on Tuesday, 17 November.
Key indicators that would signal a decisive shift in the coalition trajectory include:
- External Support: Any softening by Liberman toward external Arab-party backing would substantially increase the viability of an Eisenkot-led minority government. It is unclear whether or not the election of Matan Kahana as speaker with the support of both Arab parties presages the formation of a minority government with outside Arab party support.
- Conscription: Formal negotiations between UTJ, Shas, and Eisenkot’s bloc over a binding compromise on ultra-Orthodox military service would indicate that a 61-seat alternative coalition is advancing.
- Leadership Rotation: Direct discussions between Netanyahu and Eisenkot’s camp regarding prime ministerial rotation or power-sharing terms would signal serious movement toward a unity government.
- Continued Stalemate: Absence of concessions across all three tracks as the 20 December final deadline approaches would point toward prolonged caretaker administration, heightened legislative-executive friction and policy paralysis, and an increased probability of new elections in late February 2027.
Key Takeaways
|
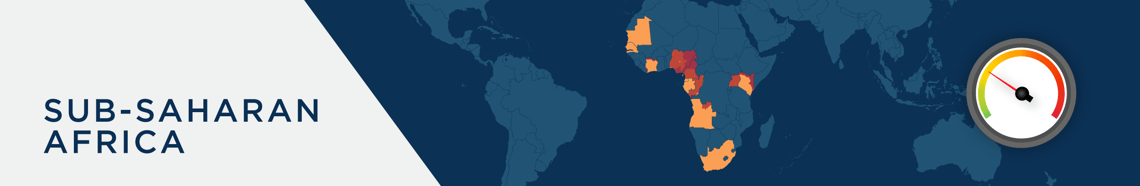
Energy Capital Flight from Persian Gulf Deepens Sub-Saharan Africa’s Exposure to Conflict and Unrest
The ongoing conflict in the Middle East has pushed substantial oil and gas investment out of the Gulf region and into Sub-Saharan Africa (SSA). Oil and gas development in Nigeria, Angola, and Mozambique leads the growth in investment, but there are also significant new or planned projects in Kenya, Coastal West Africa, Gabon, Cameroon, Equatorial Guinea, Uganda, and the Republic of Congo. This shift in global energy capital comes in the context of increasingly effective jihadist movements in the Sahel, rising interstate conflict in the Horn and Great Lakes regions, pervasive civil unrest throughout the continent, and growing state interest in resource nationalism. The inflow of energy capital into Africa is unlikely to mitigate these risk dynamics, and in some cases is likely to exacerbate them, exposing investors, operators, and their host countries to destabilization and insecurity.
Recommendations
- Firms and travelers should anticipate the possibility of deteriorating security environments around major energy sites.
- Businesses should also expect recurring fuel price and land rights protests in host countries as revenues, subsidies, and compensation become sources of grievance.
- Global Guardian strongly recommends low-profile secure transportation and pre-trip intelligence for all travel to energy project sites in Sub-Saharan Africa.
- Firms with facilities in Sub-Saharan locations should assess their fuel security with respect to both their supply in the case of fuel scarcity, as well as their exposure to fuel theft from company vehicles, generators, or other fuel sources.
Situation Report
Sub-Saharan Africa’s upstream oil and gas sector is projected to attract roughly $40 billion a year of investment through 2030, with Mozambique, Nigeria, Angola, and Côte d’Ivoire accounting for the largest shares. Sub-Saharan liquefied natural gas (LNG) exports are likewise forecast to rise nearly 175% to 98 billion cubic meters (bcm) by 2034, up from 35.7 bcm in 2024. Some of the largest projects driving this growth are in Nigeria, Kenya, Mozambique, Senegal, Mauritania, and Côte d’Ivoire, each facing at least one major risk dynamic.
Nigeria
Nigeria is home to the world's largest oil refinery and is central to the continent's oil and gas network. Nigerian billionaire Aliko Dangote is responsible for the larger part of Sub-Saharan Africa's domestic oil and gas investment, and his company Dangote Industries owns roughly 15% of Africa's total refining capacity.
Local Risks: Boko Haram, endemic banditry, and organized oil theft and smuggling groups pose risks to exploration and production. Criminal networks in the Niger Delta area specializing in onshore and riverine theft are responsible for siphoning 120,000 barrels of crude oil a day from the licit market, accounting for nearly 6% of national output.
Kenya
In October 2026, Aliko Dangote and President William Ruto broke ground on a $16 billion refinery in Lamu designed to process 700,000 barrels of crude a day.
Local Risks: The Dangote East Africa Petroleum Refinery has already incited protests, legal challenges, and political opposition. Significant youth-led demonstrations against inequality, corruption, cost of living, and bad governance have taken place regularly over the course of Ruto's presidency, with some protests specifically citing grievances against foreign firms and energy costs.
- Surging fuel prices sparked deadly protests in Kenya in May 2026, and in September of 2024, hundreds of travelers were stranded when workers at the Jomo Kenyatta International Airport went on strike in protest of the facility's proposed sale to a foreign firm. Outside investment that the Kenyan public identifies as responsible for rising costs is very likely to be a target of future unrest.
Mozambique
TotalEnergies’ $20 billion Mozambique LNG project resumed construction in January 2026 and is around 45% complete. Eni’s Coral North FLNG project is estimated at $7.2 billion and ExxonMobil’s $30 billion Rovuma LNG project is advancing toward a final investment decision targeted for late 2026.
Local Risks: Oil and gas development in Mozambique, which is concentrated in the restive Cabo Delgado Province, is one of the largest drivers of Sub-Saharan Africa’s recent LNG growth. Despite security collaboration with Rwanda, the Islamic State Mozambique (ISM) still poses a serious threat to infrastructure development in the area. At least 6,632 people were killed in instances of political violence in Cabo Delgado between October 2017 and 14 June 2026, including 2,772 civilians. Recently, ISM fighters killed at least 19 people between 21 and 31 October 2026 and were active in nine of the province’s districts that month.
- Efforts to address the non-state-actor-driven risks like ISM are complicated by interstate tensions. Rwanda’s peacekeeping force in Mozambique, for example, has been used by Kigali as a diplomatic lever to protect itself from Western sanctions imposed on its military for its continued backing of the M23 militia in the DRC. In March 2026, the U.S. sanctioned Rwandan army officials and the Rwanda Defense Force over their continued support for M23. That month, Rwanda’s foreign minister said Kigali will withdraw its troops from Mozambique unless foreign backers maintain sustainable funding.
West Africa
Senegal and Mauritania are beginning a second phase of the Greater Tortue Ahmeyim offshore LNG project, which is set to add 2.5–3 mtpa for an estimated $3–5 billion.
In Côte d’Ivoire, Eni’s Baleine Phase 3 aims to raise output to 150,000 bpd, with first production expected by January 2029.
Local Risks: Projects in coastal West African countries, including Côte d’Ivoire and Senegal, are exposed to growing insecurity in the Sahel, where the military juntas leading Mali, Niger, and Burkina Faso are fighting Jama’at Nusrat al-Islam wal-Muslimin (JNIM) and other organized insurgent groups.
- For Senegal and Mauritania, the jihadist threat is particularly acute given their proximity to Mali, where JNIM has pursued effective fuel blockades that target oil and gas assets and personnel specifically.
- Since JNIM announced the blockade of Bamako on 03 September 2025, over 300 fuel tankers have been destroyed en route from Senegal, Côte d’Ivoire, and Guinea.
Analysis
The injection of large volumes of capital into this threat landscape will likely exacerbate these risks in some areas.
Inequality within countries, particularly in countries that suffer from endemic corruption, is a direct driver of civil unrest. Kenya's wave of protests over the past several years has been based on the popular perception that economic growth disproportionately enriches a small coterie of elites at the cost of the general public. This same dynamic is present across the continent, including in Nigeria and Senegal where populist anti-corruption protests took place in 2024, in Senegal's case leading to the loss of long-time incumbent President Macky Sall.
Even the supposed winners of the rising cost of oil and increased investment are exposed to the risks generated by economic disparities and foreign ownership. Angola, for example, is a major oil and gas producer where primary hydrocarbon exports account for over 90% of the country's exports and 40% of fiscal revenue. But the country also imports the overwhelming majority of its refined fuel products, which are subsidized to the cost of roughly $3 billion a year, more than the government spends on health and education combined. In the past year, even with the sharp rise in crude prices, Angola's petrol windfall was more than erased by the rise in the cost of refined fuel products and consequent rise in subsidy spending.
The removal of fuel subsidies like Angola's would balance state ledgers but invariably incite some level of civil unrest. Deadly protests erupted when subsidy reductions or repeals were previously attempted in Angola in 2025, Nigeria in 2023, and Kenya in 2026. Angola’s July 2025 fuel protests left 22 dead, 197 injured, and 1,214 arrested.
As foreign investment in exploration and production increases, refining investment has lagged substantially, opening more countries to the possibility of financial and social strain from the internal disparity between winners and losers. This is primarily because conspicuous foreign ownership of national resources in high-inequality economies has proven politically harmful for governments across Africa. The Dangote refinery in Kenya, for example, has been politicized with Kenyan presidential aspirant Patrick Osoi vowing to halt the project and "send Dangote home" if elected in 2027. The coups in Mali (2021), Burkina Faso (2022), and Niger (2023) were rhetorically justified as anti-colonial movements seeking to end foreign extraction, and Ousmane Sonko's ousting of Senegalese President Macky Sall was billed as the end of an era of compliance with French exploitation.
Looking Forward
Sub-Saharan Africa is set to take on a more central role in the global energy economy. The disparity between the countries that are positively and negatively impacted by energy investment will likely reshape the geopolitical dynamics of the continent and instigate international friction.
Dependence on Nigerian refining capacity is already emerging. South Africa, Kenya, and Ghana all approached Nigeria’s Dangote Refinery for fuel deals after Middle Eastern supplies were disrupted. Rwanda’s leverage over Cabo Delgado shows how security guarantees for energy assets can become bargaining chips between states.
Investment on the continent may end up in the same position as investment in the Gulf, as multiple conflicts could imperil significant portions of the new projects driving energy growth.
Key Takeaways
|
CUSTOM INTELLIGENCE
Our intelligence analysts provide in-depth custom reports—including critical insight from on-the-ground resources—for clients and organizations in need of real-time analysis of world events with the potential to impact business operations. To learn more—and start building your report—complete the form below.